Equity Release Cost & Impact Calculator
Estimate how much you will owe in the future when using a Lifetime Mortgage. This tool demonstrates the power of compounding interest on equity release loans.
Total Debt at End of Term
€0
Principal + Compounded InterestInterest Paid:
€0
Remaining Equity:
€0
Inheritance Impact Analysis
Assuming home value remains static (no growth):
Enter your details and click "Calculate Impact" to see how compound interest affects your estate.
You’ve lived in your house for twenty years. The mortgage is gone. The kids have moved out. You’re sitting on a pile of cash trapped in the walls and roof of your own home. It’s tempting to tap into that money. But releasing equity is a financial strategy where homeowners access the accumulated value of their property without selling it outright. Is it actually a good thing? Or is it just a fancy way to eat your future inheritance?
The answer isn’t yes or no. It depends entirely on what you need the money for and how long you plan to stay put. For some retirees, it’s the difference between struggling to pay heating bills and enjoying a comfortable life. For others, it’s a debt trap that compounds interest until there’s nothing left for the heirs. Let’s break down the reality, not the marketing brochures.
What Actually Happens When You Release Equity
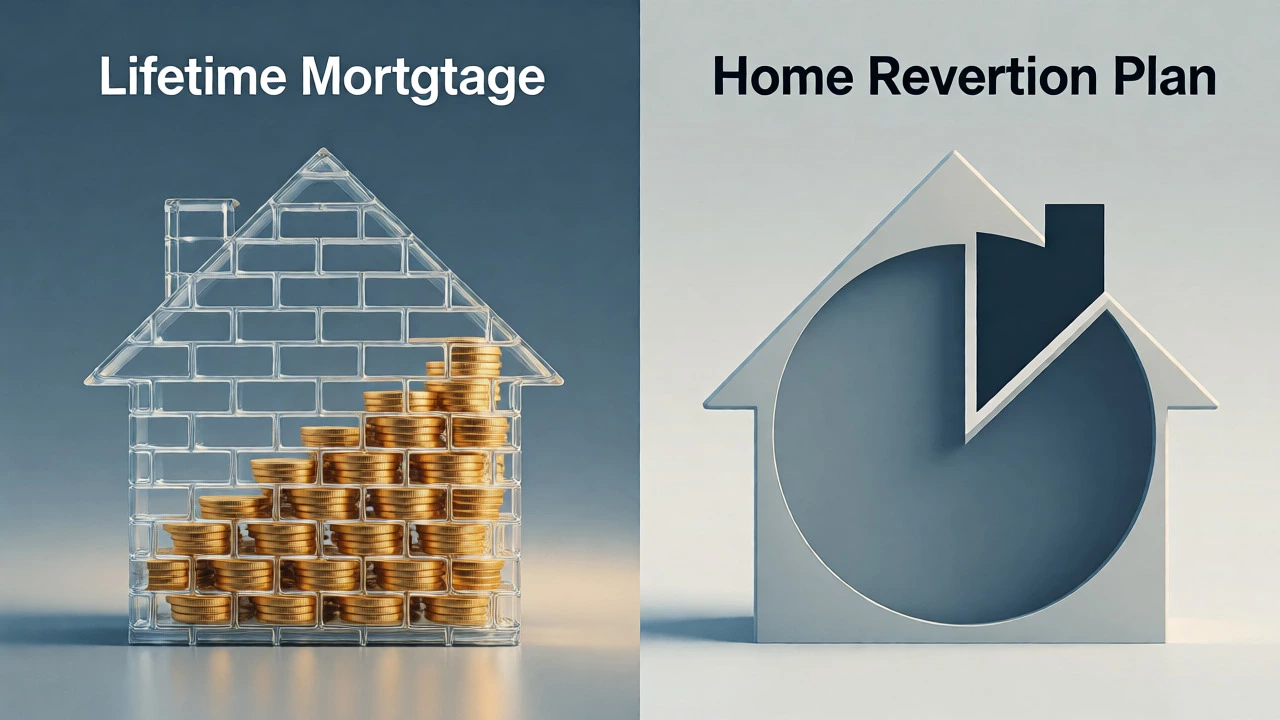
Think of your home as a savings account with high entry fees and weird withdrawal rules. When you release equity, you aren’t selling your house. You’re borrowing against its value. There are two main ways this works, and they behave very differently over time.
The first is a Lifetime Mortgage. This is the most common product in Ireland and the UK. You borrow a lump sum or a drawdown facility. No monthly repayments are required. Instead, the interest rolls up. This means you owe more next year than you do today, even if you haven’t touched the money again. The loan is repaid when you die, move into long-term care, or sell the house.
The second option is a Home Reversion Plan. Here, you sell a portion of your home to a provider in exchange for a tax-free lump sum. You keep living there rent-free for the rest of your life. If you sold 50% of your £300,000 home, you might only get £100,000 cash now, because the provider needs to make a profit when they eventually sell the full property decades later.
| Feature | Lifetime Mortgage | Home Reversion |
|---|---|---|
| Cash Received | Up to 60-70% of home value | Often less than market share value |
| Debt Growth | Yes, compounding interest | No debt, but reduced asset ownership |
| Inheritance Impact | Reduces estate by loan + interest | Children inherit smaller share of property |
| Best For | Those wanting to keep full ownership title | Those who don’t mind losing part of their home |
The Case For: Why People Do It
Let’s look at the positives. If you’re retired and your pension is modest, your house is likely your biggest asset. Releasing equity can unlock funds for things that actually improve your quality of life right now.
- Clearing Existing Debt: Many older homeowners still carry credit card balances or personal loans from when they were working. Paying off high-interest debt (often 10-15%) using lower-rate equity release (often 4-6%) makes immediate mathematical sense.
- Home Improvements: Installing a ground-floor shower, widening doorways, or adding a stairlift allows you to age in place. Moving to a bungalow costs thousands in stamp duty and moving fees. Renovating your current home is often cheaper.
- Helping Family: Grandparents often use released equity to help children with deposit assistance or grandchildren with tuition. It’s a gift while you’re alive, so you see the impact.
- No Monthly Payments: Unlike a traditional remortgage, you don’t need to prove income to service the loan. This removes the stress of monthly outgoings on a fixed pension.
Consider Mary, 72, in Dublin. Her pension covers basics, but she wants to travel once before her health declines. She releases £40,000. She doesn’t pay back a cent during her lifetime. She travels, enjoys her last active years, and leaves the debt to be settled from the sale proceeds after she passes. To her, that’s a win.
The Case Against: The Hidden Traps
Here is where the "good thing" label gets shaky. The biggest enemy of equity release is compound interest. Because you aren’t paying the interest monthly, it gets added to your loan balance. Next year, you pay interest on your original loan plus the previous year’s interest.
If you take a £50,000 loan at 5% interest, after ten years, you don’t owe £75,000 (simple interest). You owe roughly £81,000 due to compounding. After twenty years, that number balloons significantly. Property prices might rise, which helps offset this, but if the housing market stagnates, your equity shrinks rapidly.
Another major downside is the impact on state benefits. In many jurisdictions, including Ireland and the UK, holding significant capital can disqualify you from means-tested supports like the State Pension Credit or housing allowances. A lump sum of €50,000 might seem small, but if it pushes your assets over the threshold, you could lose thousands in annual benefits. Always check the specific rules in your region before signing.
Then there’s the inheritance factor. Your children might expect to inherit the family home. If you release half the equity, and interest doubles the debt over thirty years, there might be little left for them. Have an honest conversation with your family. Are they okay with a smaller inheritance in exchange for seeing you enjoy your retirement? Or will they resent the decision later?
Costs and Fees You Can’t Ignore
Equity release isn’t free. The upfront costs can eat into your lump sum significantly. Before you sign, ask for a breakdown of these charges:
- Arrangement Fee: Often ranges from €500 to €1,500 depending on the lender.
- Valuation Fee: The lender needs to know what your home is worth. This usually costs €150-€300.
- Legal Fees: You must have independent legal advice. Expect to pay €1,000-€1,500.
- Advice Fee: Regulated financial advisors charge for their guidance, typically €500-€1,000.
On a €30,000 release, these fees could total nearly €3,000. That’s 10% of your cash gone before you spend a cent. Some providers offer "no fee" deals, but they often compensate with higher interest rates. Run the numbers over 10, 15, and 20 years to see which option saves you more in the long run.
Who Should Avoid Releasing Equity?
It’s not for everyone. You should probably skip it if:
- You plan to move soon: Early repayment charges (ERCs) can be brutal. If you leave within the first 5-10 years, you might face penalties costing thousands.
- You have other liquid assets: If you have savings earning decent interest, spending those first preserves your home equity.
- You rely on means-tested benefits: As mentioned, cash savings can reduce your eligibility for state support.
- You want to leave a large estate: If leaving a substantial inheritance is a non-negotiable goal, equity release erodes that legacy.
A Practical Checklist Before Signing
Don’t rush. Take your time. Use this checklist to protect yourself:
- Get Independent Legal Advice: Never let the provider’s lawyer handle everything. Hire your own solicitor who specializes in equity release.
- Check the "No Negative Equity" Guarantee: Ensure the contract states you will never owe more than the property’s value when it’s sold. This protects you if house prices crash.
- Review Interest Rate Types: Fixed rates offer security; variable rates can go up or down. Given inflation risks, a capped variable rate might be safer than a low introductory fixed rate that spikes later.
- Talk to Your Children: Get them involved early. Surprise debts cause family friction after you’re gone.
- Compare at Least Three Providers: Rates vary significantly. A 0.5% difference sounds small but adds up massively over 20 years.
Alternatives to Consider First
Before tapping your home, look at other options. Could you downsize? Selling a large four-bed semi-detached house and buying a smaller apartment might release tens of thousands in cash without any interest accruing. You’d also save on maintenance and energy bills.
Could you reverse-mortgage through a standard bank? Some banks offer "retirement mortgages" where you pay interest monthly. If you can afford small payments, this prevents the debt snowball effect seen in lifetime mortgages.
What about unsecured personal loans? If you need a small amount (under €10,000), a personal loan might be cheaper and simpler than setting up a complex equity release scheme.
Does releasing equity affect my taxes?
Generally, the cash you receive from equity release is considered a loan, not income, so it is usually tax-free. However, if you invest the lump sum and earn interest on it, that investment income may be taxable. Additionally, holding large sums of cash can affect your eligibility for means-tested government benefits, which indirectly impacts your net finances.
Can I stay in my home if I release equity?
Yes. Both Lifetime Mortgages and Home Reversion plans allow you to remain in your property for the rest of your life, provided you continue to maintain the home, pay buildings insurance, and cover council rates or property taxes. You retain the right to live there regardless of whether you sell or pass away.
What happens if I want to move house?
Most modern equity release products are portable, meaning you can transfer the loan to a new property. However, the new property must meet the lender's criteria, and you may need to top up the loan if the new home is less valuable. Check for early repayment charges if you decide to sell and not buy another home immediately.
Is there a risk of losing my home?
The risk is low if you choose a reputable provider with a "No Negative Equity" guarantee. This ensures the debt never exceeds the property's value. However, you must keep up with maintenance and insurance obligations. Failure to maintain the property could technically breach the contract, though lenders rarely repossess homes solely for minor maintenance issues unless the property becomes uninhabitable.
How much equity can I release?
Typically, you can release between 20% and 60% of your home's value. The exact percentage depends on your age, health, and the property type. Older applicants (e.g., 75+) can usually release a higher percentage than younger ones (e.g., 60+). Health conditions like smoking or certain medical issues can sometimes increase the available percentage.